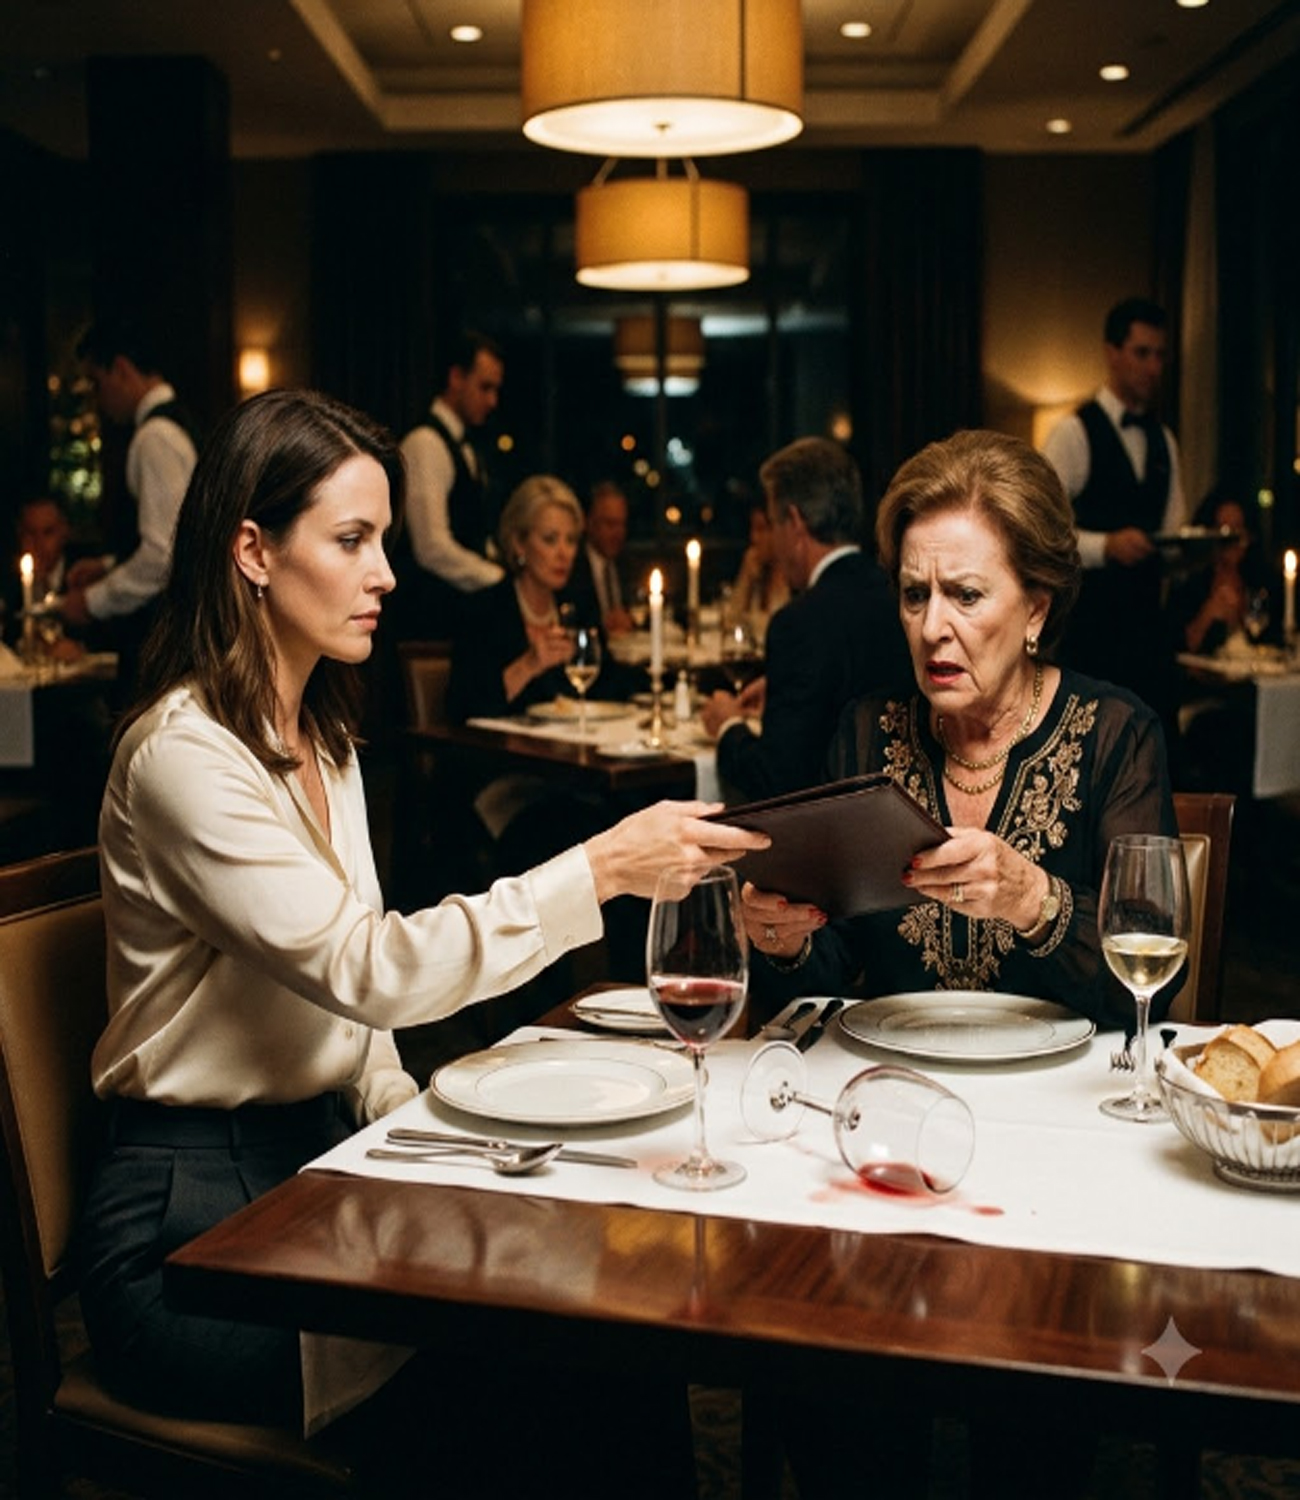
“Is this a check?” my sister-in-law asked when I handed her the folder at her birthday dinner. “We always split it evenly. That’s how we do it.” Not tonight. Inside was an itemized bill — three shrimp cocktails, two bottles of Malbec, extra bread she’d waved in like it was free. $412. Her table. Nobody else’s. She turned to my husband, chin first, waiting for him to fix it the way he always fixed things by absorbing the cost and smoothing the moment over. He looked at his steak, then at me, then at her. “It’s her call tonight,” he said. I’d finally taught them a lesson — but that was just the beginning of what I’d uncover.
“Is this a check?” my sister-in-law asked when I handed her the folder at her birthday dinner. “We always split it evenly. That’s how we do it.” Not tonight. Inside was an itemized bill — three shrimp cocktails, two bottles of Malbec, extra bread she’d waved in like it was free. $412. Her table. Nobody else’s. She turned to my husband, chin first, waiting for him to fix it the way he always fixed things by absorbing the cost and smoothing the moment over. He looked at his steak, then at me, then at her. “It’s her call tonight,” he said. I’d finally taught them a lesson — but that was just the beginning of what I’d uncover.
Detective Marcus Whitfield of the county’s financial crimes unit called me back within two hours of my report. He’d been with the department for 14 years, the last six in financial crimes specifically. He had the particular gentleness of a man who had learned that people calling him are usually mid-collapse.
“Walk me through the timeline,” he said slowly. “I’d rather take longer and get it right.”
I told him about the anniversary account. About Serena. About the $850 that had started this and the $2,140 that I now knew followed it. About the dinner. About the authorized signer form with my forged signature and the $40,000 sitting five days from release.
“Does your husband know about the HELOC form?”
“I don’t know.”
“Would he have access to make a change like that on his own without your consent?”
“He’s a co-owner on the account. Technically, yes.”
“Then I need to ask you something, and I want you to think carefully before you answer. Is it possible your husband signed your name himself?”
I hadn’t let that question fully surface in my own head until a detective said it out loud in a tone that made it impossible to keep dodging.
“I don’t know,” I said again. This time it came out smaller.
“We’ll pull the bank’s electronic upload metadata. Timestamp, IP address, device ID. If we’re lucky, that’ll tell us who submitted the document regardless of whose name is signed on it.”
“In the meantime, I want you to document everything. Every text, every conversation, every dollar. And Mrs. Voss, don’t confront anyone yet. Let the metadata talk first.”
The metadata took three days to come back. And those three days were the strangest of my marriage because I had to sit across the dinner table from Chris every night, pretending I didn’t know a felony might be sitting in our joint credit history.
I used the time instead. I called a family law attorney, Patricia Alvarez, whose name I’d found through a friend from work who’d gone through her own divorce. Patricia’s office was small, unglamorous, and full of filing boxes that told me she was the kind of lawyer who actually read every page.
“I’m not saying divorce,” I told her, sitting across from her desk. “I’m saying I need to know what my options are if it turns out my husband forged my signature on a joint credit line.”
“Then let’s talk about what you’re protecting,” she said. “Your house, your credit, and depending on what the detective finds, possibly your husband’s freedom — whether you want to protect that or not. Those aren’t the same fight, and you don’t have to decide today which one you’re fighting.”
“But I want you prepared if his signature turns up on that upload. And it likely will. Forgery of this kind is prosecutable regardless of family relationship. Prosecutors don’t care that he’s your husband. They care whether a crime occurred.”
“What if I don’t want him prosecuted? I just want the money back and the account fixed.”
“Then we build toward a civil resolution and let the bank’s fraud department close it out administratively, assuming they’re willing, which most banks are if the funds haven’t dispersed.”
“But Mrs. Voss, and I say this as someone who has sat across from a hundred women in your exact chair, decide that because it’s what you want — not because you’re still hoping this turns out to be a misunderstanding. It isn’t. Forged signatures aren’t misunderstandings. They’re decisions.”
I left her office with a folder of my own — retainer paperwork, a checklist of documents to gather, and a business card for a forensic accountant. His name was Daniel Reyes, CPA, and he had the unhurried patience of a man who had spent 15 years finding money that other people had tried very hard to make disappear.
I brought him six months of statements from the anniversary account, the HELOC documentation, and at his request, three years of joint account history I hadn’t thought to pull before.
He called me back nine days later with a spreadsheet that made my stomach drop for the second time in a month.
“This didn’t start two months ago,” he said. “It started roughly two years ago, right around the time you opened the home equity line. Small, irregular withdrawals from your joint checking, timed almost always within 48 hours of a family gathering. I count 31 transactions over that period, totaling just under $9,000 before we even get to the anniversary account and the HELOC attempt.”
“$9,000 give or take. I want to be conservative with the number until we finish reconciling a few ambiguous entries. But Mrs. Voss, I’ll be direct with you because I think you’d rather have direct. This has the pattern of something sustained and deliberate, not a one-time lapse in judgment. Whoever was managing these withdrawals understood exactly how to keep each one under the threshold that would trigger a fraud alert on your account. That’s not carelessness. That’s method.”
I thought about every “I’ll pay it back” Chris had ever said to me across three years and did the math on how many of those had been true. None. When I finally let myself add it up, the answer was none.
Detective Whitfield called on a Tuesday afternoon while I was still at work. I had to step into the stairwell of my office building to take it because I already knew from the particular flatness in his voice when he said my name that whatever came next would not be a surprise so much as a confirmation.
“The upload metadata puts the document submission at 11:52 PM on a Thursday from a device registered to your husband’s phone number. The IP address traces to your home network. It was him.”
“It was submitted from his device on your network at a time you told me he was awake and you were asleep. I can’t tell you with certainty who physically typed the signature without a handwriting exam, but I can tell you the submission wasn’t made by anyone outside your household, and it wasn’t made by you.”
I stood in that stairwell for a long moment, watching the fluorescent light flicker over the exit sign, and felt something in me stop bracing for a version of this story where I was wrong.
“What happens now?”
“Now I bring him in for an interview. Voluntary at first — gives him a chance to explain himself before this becomes formal. I’d encourage you to let your attorney handle contact with him from here rather than confronting him yourself. Emotional confrontations tend to give people time to get their story straight before they’re on record.”
“And the $40,000 is still frozen pending resolution. He’s not getting that money, Mrs. Voss. Not for his sister’s down payment. Not for anything until this is sorted.”
I hung up and sat with the phone in my lap for a long time. Five days. That’s what Priya had said back when this was still just a suspicious form and not a confirmed crime. Five days until the disbursement date. Whitfield’s interview with Chris was scheduled for the fourth day, which meant I had one day of not knowing, followed by one day where I’d know everything, followed by whatever came after.
And no version of that timeline let me pretend, even for an afternoon, that this was still fixable with a conversation.
I didn’t sleep. I kept doing the math instead. $9,000 from the joint account. $2,140 from the anniversary fund. $40,000 almost gone to a house that wasn’t mine. Three years of dinners nobody had ever itemized before that folder.
And somewhere around 3 AM, I understood that I wasn’t waiting for Whitfield to tell me something new. I already knew. I was waiting for someone else to say it first so I wouldn’t have to be the one who ended my own marriage out loud.
ACT 2 — Context & Escalation
My hands wouldn’t stop shaking that whole day at work. I dropped a mug in the breakroom and didn’t pick up the pieces right away. Just stood there looking at them scattered across the tile, thinking that’s what this is going to look like too.
I had 24 hours before Detective Whitfield’s scheduled interview with Chris. And in that window, Serena called me for the first time since the birthday dinner.
“I heard the HELOC transfer got held up,” she said. No hello, no preamble. Straight into it the way she always did when she wanted something.
“The seller’s giving us until Friday or the house goes to another buyer. Whatever is wrong with the account, can you fix it? We’re this close.”
“Serena, do you know where that $40,000 was supposed to come from?”
“Chris said you two set it aside for us for the down payment. He said it was a gift.”
“It’s not a gift. It’s a home equity line against my house. And someone forged my signature to add you as an authorized user on it.”
The silence on the other end of the line lasted long enough that I could hear her kitchen in the background. A dishwasher running. A child’s cartoon somewhere in another room.
“He told me you already agreed to it,” she finally said, quieter now.
“I never agreed to anything. I found out because the bank flagged the form for fraud. There’s a detective involved. Serena, your name is on a document connected to a forgery investigation.”
“I didn’t forge anything.”
“I believe you. But you’re still on it. And you’re going to want your own lawyer before this goes any further. Because right now, the only story anyone can prove is that my husband submitted paperwork with my forged signature to get you money he had no right to give.”
She hung up without another word. And for the first time in three years of dinners and declined cards and nicknames said in front of waiters, I heard something in her voice that wasn’t entitlement. It was fear.
It suited her better than the entitlement had.
Chris’s interview with Detective Whitfield happened on a Thursday morning. I wasn’t there. Patricia had advised me strongly against it. And for once, I listened to advice I didn’t want to hear.
What I got instead was a phone call from Chris that evening. His voice stripped down to something I hadn’t heard from him since the early years of our marriage — before he’d learned that silence and vague promises usually got him through.
“I told him the truth,” he said. “I signed it. I thought — I don’t know what I thought. Serena needed the down payment by a deadline, and I knew you’d say no if I asked. So I told myself I’d just move it and explain later. And later kept not coming. And then the bank flagged it before I could.”
“Before you could what, Chris? Tell me the version where this ends with you fixing it instead of me finding it.”
“I know how it looks.”
“It doesn’t look like anything. It is what it is. You forged my name on a document tied to a felony to give your sister money out of my house. After two years of quietly draining our accounts every time your family needed something and you didn’t want to be the one who said no.”
He didn’t argue with any of it. That was almost the worst part. Three years of watching him dodge every hard conversation with vagueness and half-answers. And the one time he finally told me the truth plainly was the one time the truth was unforgivable.
“Am I going to be charged?” he asked.
“I don’t know. That’s between you and the district attorney now. I’m not protecting you from this, Chris. I spent three years protecting your family’s comfort at the expense of my own. And I’m done being the only adult who pays the bill.”
The district attorney’s office ultimately offered Chris a deferred prosecution agreement — restitution in full, financial monitoring for two years, and a clean record if he completed both conditions. Contingent on my willingness as the victim of record to support the arrangement rather than push for formal charges.
Patricia walked me through the decision over three separate meetings, laying out what a trial would cost in time and exposure against what a guaranteed restitution agreement could recover without one. I chose restitution — not for him. For the $11,140 I wanted back in accounts that were, as of the day I signed our separation papers, entirely and only mine.
The divorce itself took four months. Patricia handled it the way she’d promised she would — no theatrics, no dragging it out for spite, just a clean division of what remained of a marriage that had been quietly bleeding out for longer than I’d let myself see.
The house sold. I kept half, plus the $11,140 in court-ordered restitution, plus something that turned out to matter more than either. The sudden, disorienting quiet of a life with no more dinners to plan around.
Serena, for her part, never bought that house. The sellers took another offer while the HELOC sat frozen. And by the time the fraud review closed, both her credit application and her patience with the situation had evaporated.
Priya’s office sent her a formal letter too. Once the bank’s internal review confirmed she hadn’t personally submitted the forged form, she wasn’t charged. But her name stayed attached to the flagged account for a full year, which apparently made her own mortgage pre-approval process at a different bank a slower, more humiliating ordeal than she’d ever admit to out loud.
I heard through a mutual friend months later that she’d stopped speaking to Chris almost entirely. Not out of loyalty to me — but because a man who’d forge a signature to fund your down payment is also a man who might eventually need something back. And Serena has never once in her life wanted to be the person who owes.
Taran never apologized directly. She sent a card for my birthday that fall with no note inside — just her signature, which I understood to be the closest thing to an olive branch she was capable of producing. I didn’t send one back. Some bridges don’t need burning. They just need to be left where they are, unused until the wood rots on its own.
Henry called me once near the end of the divorce in a conversation I hadn’t expected and didn’t ask for.
“I should have said something a long time ago,” he said. “About the dinners. About all of it. I let it happen because it was easier than fixing it. And I want you to know I see that now.”
“Thank you for saying that.”
“For what it’s worth, the birthday dinner — the separate checks — that was the first time in years I actually enjoyed watching my family eat.”
I laughed. Actually laughed for the first time in weeks, standing in an apartment I hadn’t finished unpacking, surrounded by boxes that held exactly what was mine and nothing that wasn’t.
It’s been eight months now. I moved 20 minutes across town into a one-bedroom with a kitchen too small for hosting anyone, which I’ve decided is a feature and not a flaw.
I opened a new savings account with a name that has nothing to do with anniversaries or trips or anyone else’s plans for my money. I call it, with zero self-awareness about the joke, the “mine” account.
Last week, I had dinner with three friends from work. The kind of dinner where the check comes and everyone reaches for their own card without discussion, without theater, without anyone waiting to see who blinks first. I paid for exactly what I ordered. Nobody called me anything but my name.
I think about that birthday dinner sometimes. The folder Serena opened. The $412. The silence that finally told me the truth about a marriage I’d been trying to balance alone.
People ask me when they hear the short version of the story whether I regret making a scene at that table. I don’t. That scene was the first honest thing that happened at any dinner with that family in three years. Everything after it — the statements, the forged signature, the detective, the deferred prosecution, the divorce — all of it just followed the trail that one folder opened.
They spent years treating me like a credit card. It turned out the real balance they owed wasn’t measured in dollars at all. It was measured in every year I spent believing that keeping the peace was the same thing as being loved.
I know the difference now. I paid full price to learn it. But for the first time in a long time, it was money I was glad to spend.
The first few months after the divorce were harder than I let myself admit. Not because I missed Chris — I realized, with some surprise, that I didn’t. I missed the version of my life I had believed I was building. I missed the future I had saved for. I missed believing that people who said they loved you would never use your trust as a line of credit.
Patricia called me once during that period, not as my attorney, but to check in. “You’re doing the hard part now,” she said. “The part where you don’t have anyone to be angry at on a daily basis, so you have to sit with yourself. That’s the part that actually changes things.”
She was right. Sitting with myself was harder than the divorce had been. The divorce had been paperwork and meetings and a clear villain. The sitting was just me and the choices I had made — the ones I had ignored, the ones I had excused, the ones I had told myself were love.
I started therapy. Not because I was broken — I was tired of that word — but because I wanted to understand how I had spent three years subsidizing people who never once asked what I needed. My therapist, a quiet woman named Elena, asked me something in our third session that I still think about.
“When did you stop believing that your needs mattered as much as everyone else’s comfort?”
I didn’t have an answer right away. I had to go back — way back — to find the beginning of it. To a childhood where I learned that being easy to love meant never asking for too much. To a marriage where I kept the peace by becoming invisible. To a pattern so old I had mistaken it for who I was.
Somewhere in the middle of that work, I stopped feeling angry at Chris and started feeling something closer to pity. Not for what he’d lost — he’d chosen that — but for the fact that he had never learned how to say no to his family. He had spent his whole life making other people comfortable at his own expense, just like I had. The difference was that I had finally stopped.
One evening, a few months after the divorce was final, I got a call from an unknown number. It was Henry.
“I know we haven’t talked,” he said. “And I know I don’t have any right to ask anything of you. But I wanted you to know that I’ve been thinking about what you said at the dinner. About the habit. About how we all just let it happen.”
He paused. “I started saying no to them. Serena wanted me to co-sign something for her new apartment, and I said no. First time I’ve ever done that. It felt terrible. But it also felt — I don’t know — clean.”
“Good for you,” I said. And I meant it.
“I’m not saying I’m fixed,” he said. “I’m just saying I’m starting to notice. And I wanted you to know that some of what you did, some of what you paid for — it didn’t go to waste. At least not on me.”
I sat with that for a while after we hung up. It was a small thing, but it was real. And real things, even small ones, are worth holding onto.
Sometimes late at night, I still open the “mine” account just to look at the number. It’s not enormous. It’s not Portugal yet. But every dollar in it came from a table where nobody handed me a folder I didn’t ask for, and nobody waited to see if I’d blink first.
I always pay for exactly what I ordered now. And for the first time in three years, that’s finally completely the whole truth.
The restaurant where the birthday dinner happened closed six months ago. A new place opened in its spot — same location, different name, different menu. I went there once, on a Friday evening, by myself. I ordered a glass of wine and a meal that cost exactly what I expected it to. When the check came, I paid it without looking at the itemization. I already knew what I’d ordered. I already knew what it cost.
That’s the part I didn’t understand before. The itemized bill wasn’t about the money. It was about the noticing. For three years, I had been paying for things I never ordered — shrimp cocktails I didn’t eat, wine I didn’t drink, bread I didn’t ask for. I had been subsidizing a family’s entitlement because no one else was willing to say “that’s yours, not mine.”
The itemized bill was just the beginning of me noticing.
I still get forwarded group chat messages sometimes. People who don’t realize I’m still on threads I left months ago. I see Serena’s name, Taran’s name, the endless planning for dinners I’ll never attend. I don’t feel angry when I see them. I feel like I’m looking at a life that used to be mine, from a distance that I put there myself.
I think about the $11,140 sometimes. The restitution. The amount Chris was ordered to pay back. It was the only time he ever paid me for all those dinners. The only time he ever acknowledged that I had been covering his family’s life instead of building my own.
I’m not building someone else’s life anymore.
I’m 20 minutes away from the house I used to share with Chris, in an apartment that is mine in a way the house never was — because I chose it for myself, not because I was trying to fit into someone else’s idea of what a family should look like.
The kitchen is too small for hosting. I’ve decided that’s a feature and not a flaw.
The savings account is growing. Slowly, but it’s growing. Every deposit is a reminder that I can choose where my money goes, and I don’t have to explain it to anyone.
Last week, a woman I work with asked me for advice. She’s in her early 30s, engaged to a man whose family has started making the same assumptions about her wallet that Chris’s family made about mine. She asked me, “How did you know when it was too much?”
I thought about the answer for a long time before I said it.
“I knew when I started keeping track,” I said. “Not of the money — of the pattern. I knew when I realized I was the only person at the table who was paying attention. And I knew when I understood that the people who loved me should never have made me the one who had to.”
She wrote it down in a notebook she kept in her bag. I saw her do it. And I thought about how long it took me to learn that sentence, and how I would have saved so much time if someone had said it to me at 25.
But you can’t save time that way. You have to spend it. You have to learn the lesson at the full price.
That’s what I paid for that dinner. And I’d pay it again.